
Stocks Market
HPS Returns to Profit as Margins Surge, Meeting Analyst Expectations
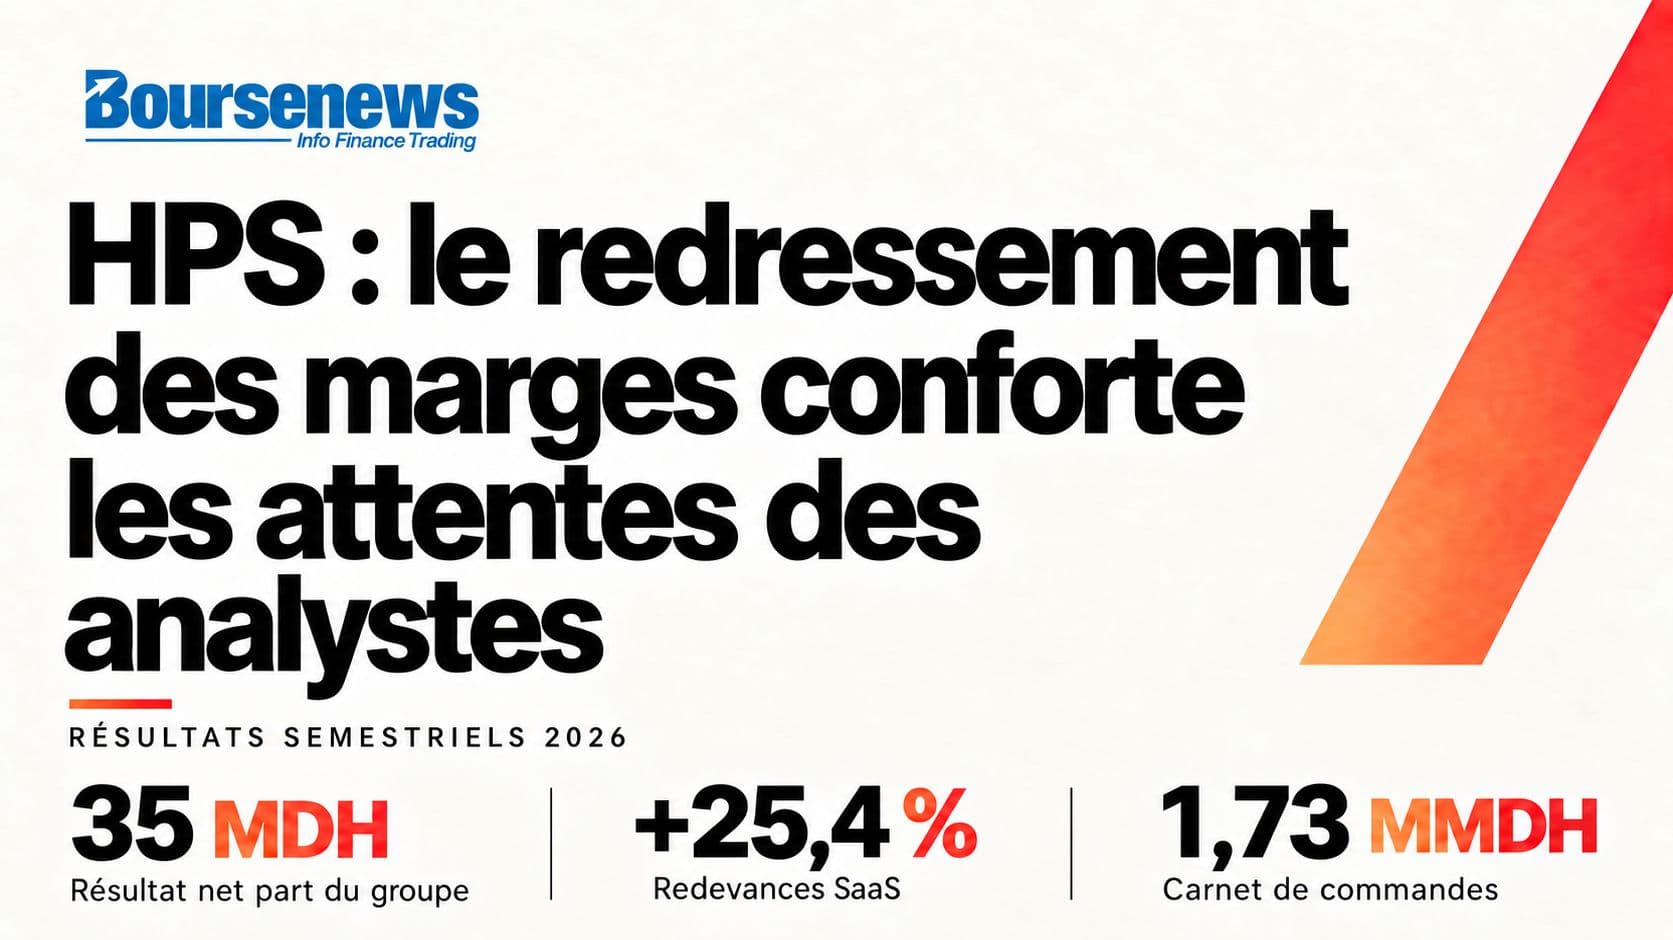
HPS posted a net profit of MAD 35 million in H1 2026, reversing a loss from the prior year, as operational margins improved and SaaS growth accelerated. EBITDA rose 74.7% to MAD 122 million, with margins expanding from 10.4% to 16%. Analysts remain bullish, citing stronger order book and robust recurring revenue. However, cash conversion remains a focus, with net cash flow from operations limited to MAD 3.7 million due to multi‑year contract timing.
Listen to this article
Unlock audio versions of premium articles and more with a Pro subscription.
HPS Returns to Profit as Margins Surge
HPS, a leading Moroccan payment solutions provider, posted a net profit of MAD 35 million in the first half of 2026, reversing a loss of MAD 47 million a year earlier. The turnaround extends the improvement begun in H2 2025 and reflects revenue growth outpacing cost increases.
Key Financial Highlights
- Operating revenue rose 13.1% to MAD 761 million, while operating expenses (excluding provisions) increased by 6%.
- EBITDA grew 74.7% to MAD 122 million, lifting the EBITDA margin from 10.4% to 16.0%.
- After eliminating exchange‑rate effects, EBITDA reached MAD 114 million (+64.1%) with a margin of 15.2%.
- Financial loss narrowed to ≈‑9 million dirhams from ‑40 million in H1 2025.
Revenue growth was driven by the PowerCARD and BankWorld projects (+33%), complementary sales to existing clients (+58.9%) and SaaS subscriptions (+25.4%). The recurring component now accounts for 69% of the total order book.
Order Book & Backlog
At end‑June, the order book reached MAD 1.73 billion, up 3.4% since December, despite project execution. New contracts signed in the semester total MAD 400 million, almost entirely in SaaS, covering solution development and up to five years of maintenance or subscription fees.
Cash Flow & Working‑Capital Impact
Despite solid earnings, cash conversion remains limited. Cash‑flow generation from operations was MAD 61 million, but the increase in working‑capital needs absorbed about MAD 73 million, leaving a net cash inflow of only MAD 3.7 million for the half‑year. HPS attributes this to multi‑year contracts where revenue is recognized gradually while invoices are issued later.
Outlook
For 2026 as a whole, HPS forecasts organic growth of 12‑17% and an improvement in EBITDA margin versus 2025, when it stood at 18.4%. The 16% margin recorded at mid‑year represents a year‑on‑year gain, while the full‑year target implies stronger second‑half performance.
The company continues to invest in cloud infrastructure, cybersecurity and compliance to support its SaaS expansion. Analysts such as CFG Bank and BKGR maintain bullish stances, with price targets ranging from MAD 705 to MAD 781.
About HPS
HPS is a Casablanca‑based provider of payment processing, banking software and SaaS solutions serving banks, retailers and fintech firms across Africa and the Middle East.