
Global Economy
European Stocks Slip Slightly Ahead of U.S. CPI Release and Middle East Tensions
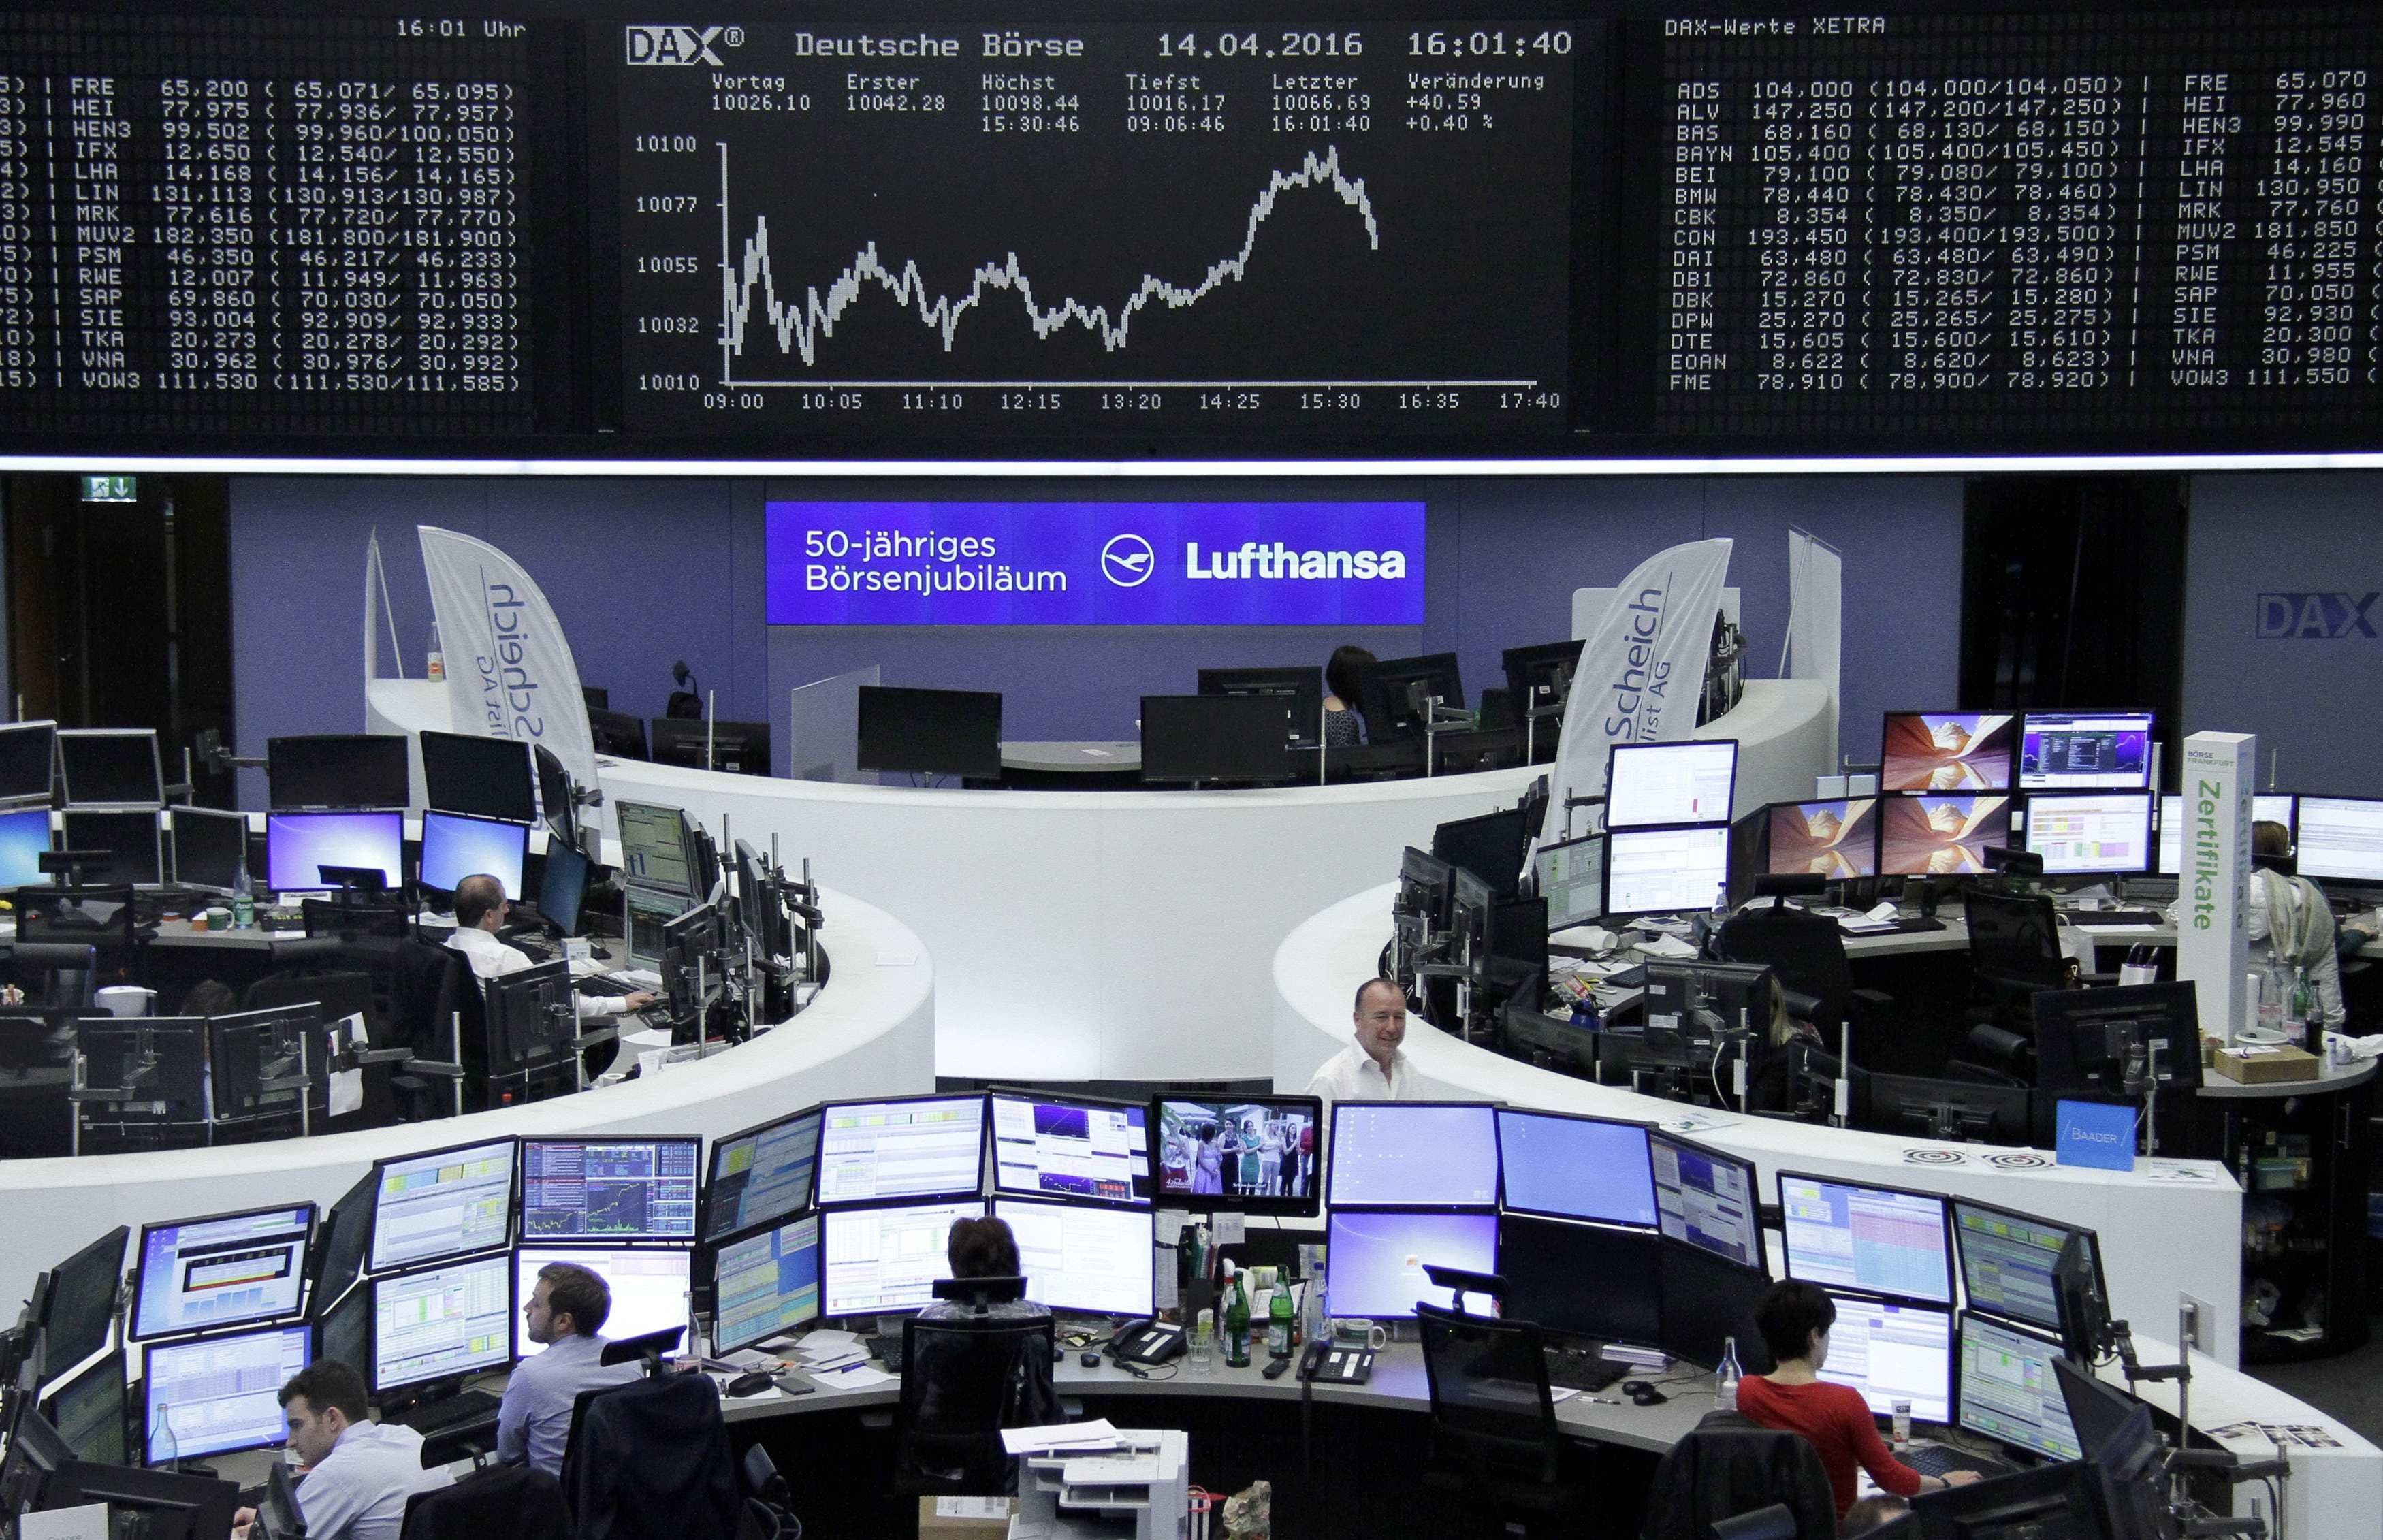
European equity markets are set to open marginally lower on Wednesday as investors await the U.S. Consumer Price Index (CPI) data that could shape the Federal Reserve’s next rate move. Oil prices remain near $90 a barrel amid ongoing uncertainty over the reopening of the Strait of Hormuz, with Iranian officials insisting on U.S. concessions. Meanwhile, Wall Street slipped on weak earnings from Amazon and Alphabet, and Asian markets showed mixed reactions.
Listen to this article
Unlock audio versions of premium articles and more with a Pro subscription.
European Markets Poised for a Small Opening Decline
At the start of Wednesday’s trading, the French CAC 40 is expected to dip by about 0.02%. Futures point to a 0.04% drop for Germany’s DAX, a 0.21% decline for the UK’s FTSE 100, and a modest 0.06% fall for the pan‑European EuroStoxx 600.
Geopolitical Uncertainty Keeps Oil Prices Elevated
Earlier reports suggested a possible agreement between Washington and Tehran to reopen the Strait of Hormuz, but Iran’s Supreme National Security Council secretary, Mohsen Rezaei, warned that the vital oil‑shipping lane will stay shut until the United States meets Iranian conditions. Recent Houthi attacks on merchant vessels have further dampened hopes for a rapid de‑escalation in the Persian Gulf.
Consequently, Brent crude is up 0.53% at $89.38 per barrel, while U.S. West Texas Intermediate (WTI) traded at $83.69, a 0.59% increase.
All Eyes on the U.S. CPI Report
The market’s focus now shifts to the U.S. Consumer Price Index, slated for release at 12:30 GMT. With energy prices still climbing, inflation pressures remain a key concern for the world’s largest economy. Nomura strategist Wataru Akiyama notes that investors are hesitant to commit to large‑scale buying ahead of the CPI numbers, as they try to gauge whether the Federal Reserve might accelerate its rate‑hiking cycle.
National Australia Bank research head Skye Masters echoed the sentiment, saying, “Everyone’s eyes are on the CPI report.”
Earnings Season Continues in Europe
While awaiting the inflation data, traders are still dissecting earnings from major European companies. The season is winding down, with results from firms such as TUI and ABN Amro on the near horizon.
Wall Street Recap
- Dow Jones fell 0.34% (‑184.13 points) to 53,791.85.
- S&P 500 slipped 0.32% (‑24.91 points) to 7,728.20.
- Nasdaq Composite dropped 0.60% (‑159.91 points) to 26,445.45.
Weak earnings from Amazon (NASDAQ:AMZN) and Alphabet (NASDAQ:GOOGL) helped drive the decline.
Asian Market Snapshot
- Tokyo’s Nikkei hovered between red and green as traders awaited U.S. CPI data.
- China’s CSI‑300 rose 0.65%, while Shanghai’s SSE Composite added 0.35%.
- Hong Kong’s Hang Seng fell 1.01%.
China Dragon Securities noted that, despite lingering uncertainties, negative pressures on markets have eased relative to July.
Bond Yields and Currency Moves
- German 10‑year Bund yield slipped 1.9 bps to 3.1584%; 2‑year to 2.7843%.
- U.S. 10‑year Treasury yield fell 0.2 bps to 4.6823%; 2‑year to 4.2157%.
- The dollar rose 0.05% against a basket of major currencies, while the euro slipped 0.04% to $1.1535.
Source: Reuters.