
Global Economy
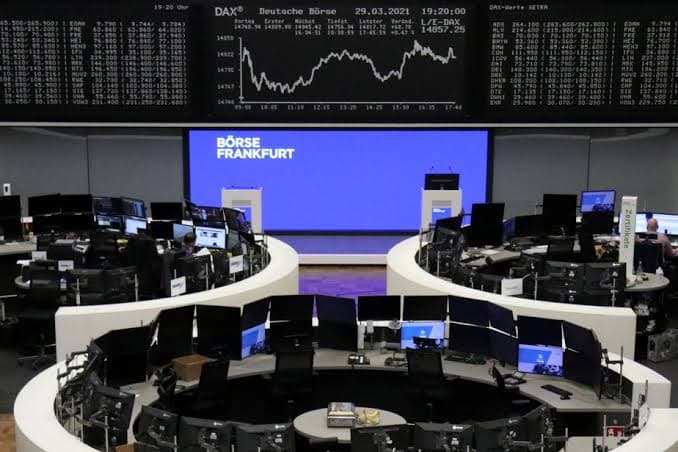
European Markets Set to Slip Amid Tech Sell‑off and Corporate Earnings
European equity indexes are expected to open lower on Tuesday as a wave of corporate earnings and concerns over artificial‑intelligence‑driven chip spending weigh on sentiment. The decline follows Asian markets that slumped on AI‑related worries, and investors will also be eyeing the Federal Reserve’s two‑day policy meeting for clues on future rate moves.
Listen to this article
Unlock audio versions of premium articles and more with a Pro subscription.
European equities likely to open lower
Major European stock markets are projected to start the day in the red on Tuesday. The downgrade follows a tumble in Asian exchanges that opened on worries about artificial‑intelligence‑related demand, which sparked a broad sell‑off in the tech sector.
Pre‑market data suggests the French CAC 40 could fall about 0.4% at the open, with the luxury sector under particular scrutiny after LVMH’s earnings release. Germany’s DAX is expected to dip roughly 0.02%, the UK’s FTSE 100 about 0.21%, the EuroStoxx 50 around 0.09%, and the broader Stoxx 600 near 0.17%.
Key earnings on the docket
European companies reporting today include Safran, Air Liquide, Orange, Kering, Soitec, EssilorLuxottica, Philips, ASM International, Barclays and Unilever. In the United States, attention will be on UPS, Coca‑Cola, Hilton, Visa and Ford, with the rest of the week featuring the big‑tech results from Microsoft, Meta, Amazon and Apple.
Tech worries and AI financing
Asian markets are tumbling as chip makers face doubts over the massive financing needed for the AI boom. Nvidia, for example, slid about 5% after the Wall Street Journal reported the company was negotiating a roughly $250 billion financing package for OpenAI’s new data‑center project.
The tech sector, highly sensitive to interest‑rate changes, is under pressure ahead of the Fed’s policy decision on Wednesday. Analysts largely expect a “hold” with the federal funds rate remaining in the 3.50 %‑3.75 % range through year‑end.
Monetary‑policy backdrop
The Bank of England and the Bank of Japan are also expected to keep their policy rates unchanged at their meetings later this week, maintaining a cautious stance amid persistent inflation concerns.
Other data releases
U.S. consumer confidence for July, released by the Conference Board, will be the only major indicator today. It precedes the release of the Q2 GDP estimate and the PCE price index – the Fed’s preferred inflation gauge – slated for Thursday.
Geopolitical notes
Oil prices have eased following a modest improvement in the Middle‑East situation, but bond markets remain jittery about a possible rate hike in the United States. Washington announced the end of its two‑week bombing campaign against Iran over the weekend, yet Tehran continues to claim control of the Strait of Hormuz despite the cease‑fire.