
Global Economy
European Markets Set to Rise on Fed Rate Pause Optimism
European stock markets are poised for gains at Friday's opening, buoyed by positive sentiment from Wall Street and Asian exchanges following dovish comments from Fed Governor Christopher Waller. The central banker signaled his preference to maintain current interest rates, easing concerns about monetary tightening despite elevated oil prices and ongoing US-Iran tensions that continue to disrupt maritime traffic through the Strait of Hormuz.
Listen to this article
Unlock audio versions of premium articles and more with a Pro subscription.
European equity indices are tracking for a positive open on Friday, following strength in both US and Asian trading sessions. Investor sentiment improved substantially after Federal Reserve Governor Christopher Waller indicated on Thursday his inclination to keep the central bank's benchmark interest rate unchanged at the upcoming policy meeting.
Pre-Market Indicators Show Modest Gains
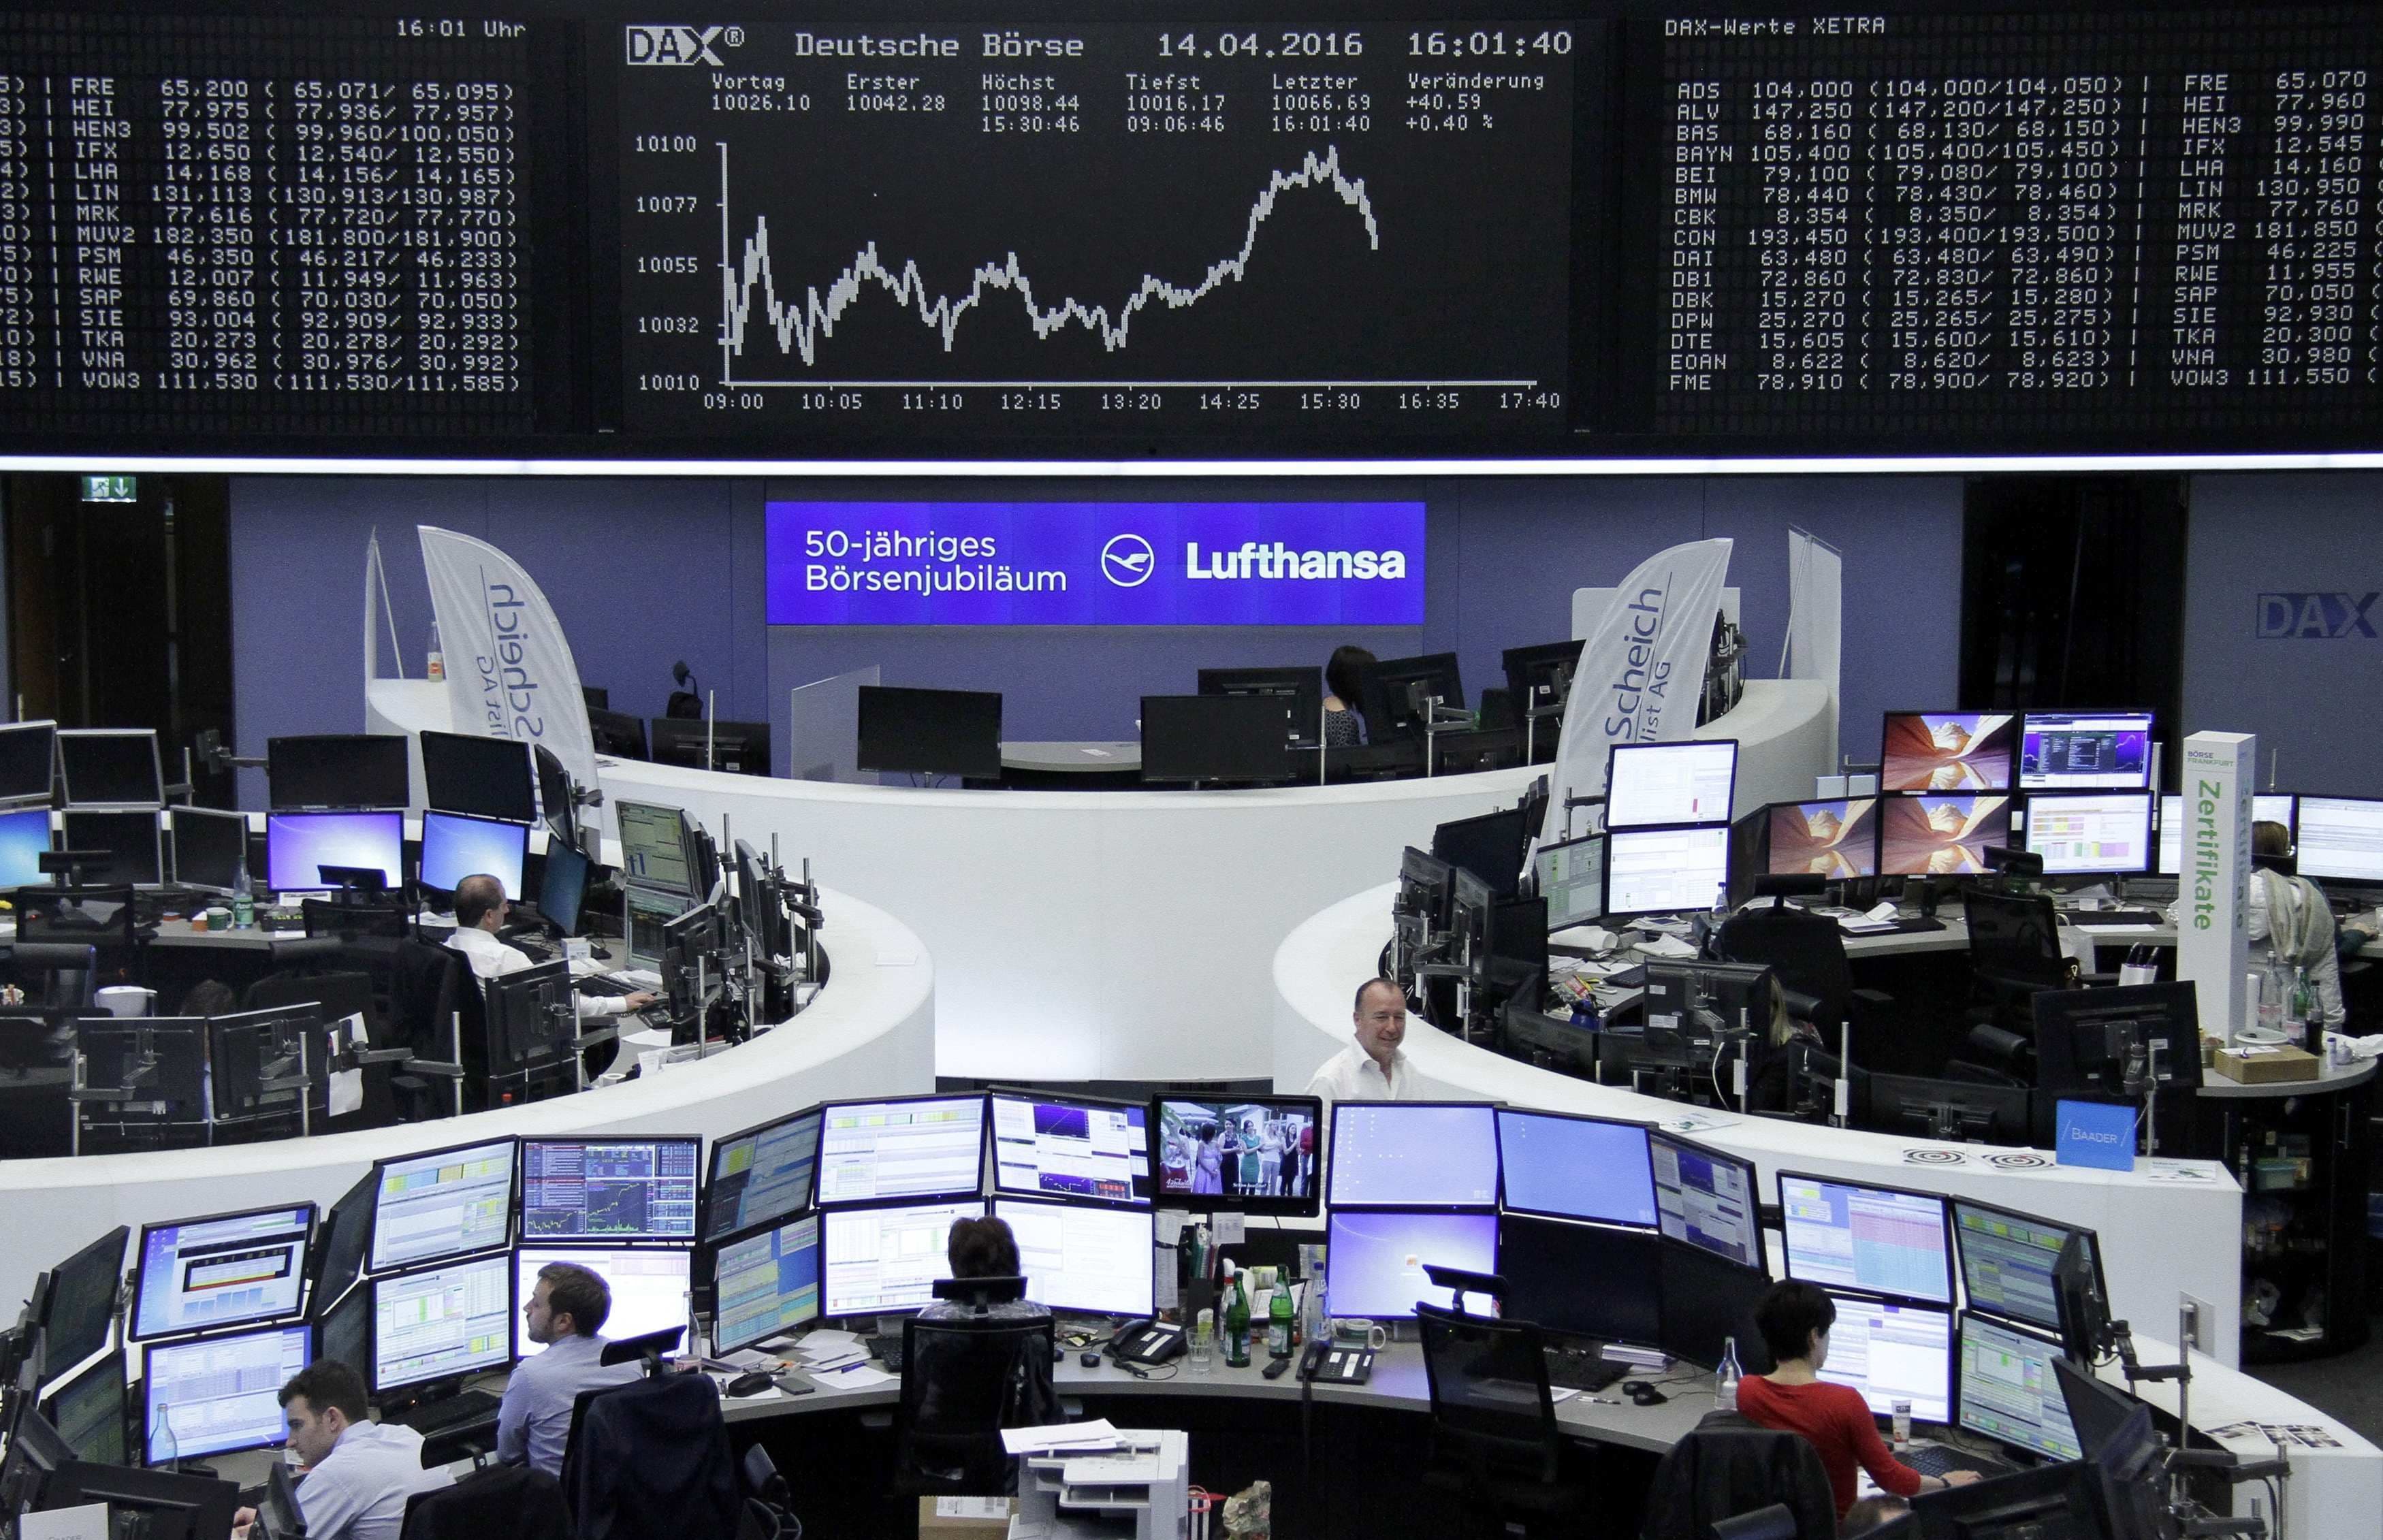
Early trading signals point to a 0.12% advance for Paris's CAC 40 index at the opening bell. Futures contracts indicate the German DAX could climb 0.23%, while London's FTSE 100 is expected to edge up 0.04%. The pan-European Stoxx 600 is forecast to gain 0.12%.
Fed Official's Dovish Stance Calms Markets
Waller's remarks helped alleviate investor concerns about potential monetary tightening, even as crude oil prices remain elevated and geopolitical tensions between Washington and Tehran persist without immediate diplomatic resolution. The ongoing conflict continues to disrupt critical shipping routes through the Red Sea, fueling inflationary worries.
"Governor Waller's statements are having a broadly positive effect across all markets," noted Bill Northey, Senior Investment Director at U.S. Bank Wealth Management in Billings, Montana.
Following these dovish comments, financial markets have adjusted their Federal Reserve policy expectations downward. CME FedWatch data now shows a 50.4% probability of a rate hike at September's Fed meeting, down from 63.2% on Wednesday.
Geopolitical Risks Remain Elevated
However, these optimistic projections remain heavily contingent on geopolitical developments and energy price movements. Preliminary maritime data released Friday revealed that only four commodity-carrying vessels transited the Strait of Hormuz on Thursday—a critical chokepoint for global hydrocarbon flows. This figure falls significantly below the ten-day average of approximately 15 ships.
"Waller is pushing back against the argument advanced by Warsh last week that there's limited evidence core inflation has moderated," JPMorgan analysts wrote in a research note. "We believe Chairman Warsh will proceed with a rate increase if he advocates for one. Governor Waller's speech reinforces our view that the data threshold required to convince the data-dependent majority to raise rates this month remains high."
US Employment Report in Focus
Market attention now turns to the US employment report scheduled for release at 12:30 GMT, which should provide additional insights into future American monetary policy. Wednesday's ADP survey showed August private sector job creation fell short of expectations, adding to the dovish narrative.
In Europe's relatively quiet Friday session, investors will analyze German industrial orders—a key indicator for the export-dependent economy that drives the continent. Eurozone retail sales figures are scheduled for late morning release.
Wall Street Rallies on Fed Relief
US markets closed sharply higher Thursday as investors welcomed the prospect of steady Fed policy if economic data shows inflation cooling. The Dow Jones Industrial Average surged 1.18%, adding 624.16 points to close at 53,686.11. The broader S&P 500 advanced 1.06%, gaining 81.11 points to 7,747.71, while the tech-heavy Nasdaq Composite jumped 1.40%, or 366.23 points, to finish at 26,584.06.
Asian Markets Follow Global Rebound
Asian bourses are participating in the worldwide rally, benefiting from reduced Fed tightening fears that have weakened the dollar and supported the yen's recovery. Tokyo's benchmark gained 1.39% to reach 65,106.87 points. Chinese markets are advancing but remain on track to close the week lower, weighed down by fading gains in artificial intelligence-related stocks and lingering concerns about US rate policy. The Shanghai Composite is up 0.59% while the CSI 300 has climbed 0.83%. Hong Kong's Hang Seng is outperforming with a 1.88% gain.
Bond Yields Ease, Dollar Steadies
In fixed income markets, the benchmark 10-year Treasury yield declined 0.2 basis points to 4.7601%, while the two-year yield fell 0.3 basis points to 4.3369%. The dollar index edged up 0.13% against a basket of major currencies. The euro gained 0.02% to $1.1626, while sterling advanced 0.07% versus the dollar and 0.09% against the euro.
Oil Prices Elevated on Supply Concerns
Crude oil prices remain elevated and are headed for their strongest weekly gains since mid-July, driven by renewed US-Iran hostilities and concerns about supply risks. Brent crude slipped 0.05% to $95.47 per barrel, while West Texas Intermediate declined 0.2% to $91.48.