
Stocks Market
Touissit Mining Company Reports 74% Revenue Surge in H1 2026, Net Cash Position Reaches 393 Million Dirhams
Compagnie Minière de Touissit (CMT) delivered exceptional financial results for the first half of 2026, posting consolidated revenues of 596 million dirhams—a 74% year-over-year increase. This remarkable growth was driven primarily by favorable zinc and silver prices rather than production volume increases, with the company maintaining relatively stable output levels. The mining company's financial position strengthened dramatically during the period, transforming from a net debt position of 70 million dirhams at year-end 2025 to a robust net cash position of 393 million dirhams by mid-year, supported by settlement receipts and operational cash generation.
Listen to this article
Unlock audio versions of premium articles and more with a Pro subscription.
Compagnie Minière de Touissit has closed the first half of 2026 with impressive financial momentum, recording consolidated revenues of 596 million dirhams compared to 343 million dirhams in the same period last year—representing a substantial 74% increase. For the second quarter alone, the company generated revenues of 255 million dirhams, marking a 47% rise.
Commodity Prices Drive Revenue Growth
Notably, this strong performance was achieved without a corresponding increase in production volumes. During the six-month period, CMT processed 174,430 tons of ore, down slightly by 1% year-over-year, while concentrate production decreased 4% to 13,400 tons. However, sales volumes increased by 17% to reach 16,096 tons, partially offsetting the production decline.
The primary catalyst for revenue expansion came from metal price appreciation. CMT benefited from a 22% increase in zinc prices and a remarkable 141% surge in silver prices, while lead prices declined marginally by 1%. The company attributes its revenue growth to these favorable commodity price movements combined with higher sales volumes throughout the semester.
Financial Structure Transformation
Perhaps the most striking development during the period involves the company's cash position. By the end of June 2026, CMT reported a positive net cash position of 393 million dirhams, a dramatic reversal from the 70 million dirhams net debt position recorded at year-end 2025. Available cash reached 408 million dirhams, while long-term debt was reduced from 70 million to just 15 million dirhams. Short-term debt was completely eliminated.
This balance sheet improvement was supported by several factors, including proceeds from final settlement agreements with OMM and Shaba Metals LLC for 35 million and 12 million dollars respectively, as well as strong operational cash generation. Additionally, a 200 million dirham short-term bank facility drawn in late March was fully repaid in April.
Capital Investment Acceleration
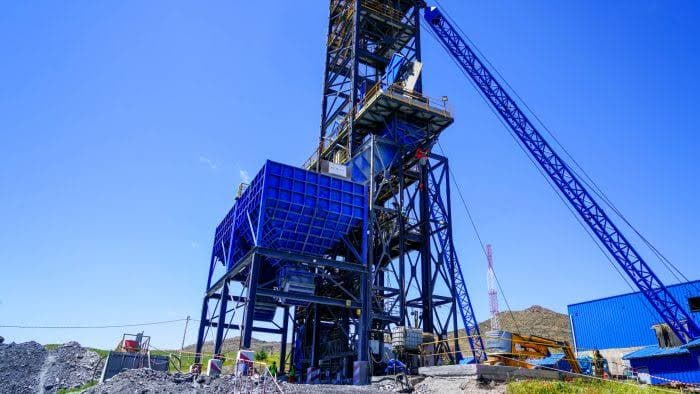
Investment spending increased during the period, reaching 37 million dirhams in the first half versus 27 million dirhams in the prior-year period—a 37% increase. Second quarter capital expenditures totaled 26 million dirhams, up 44%. CMT linked this spending growth to the completion of major work on the new Ighrem Aousser shaft, as well as expenditures for production facility maintenance, optimization, and exploration programs.
The company also conducted capital increases at its subsidiaries MINREX and CMC for 17 million and 3 million dirhams respectively.
Strategic Development Initiatives
On the development front, CMT continues advancing the certification of its reserves under the NI 43-101 standard, ramping up operations at the new Ighrem Aousser shaft, and diversifying its portfolio toward copper, gold, antimony, and graphite. The semester was also marked by the acquisition of OSEAD Fund by Ayrad Group Limited and the transition to joint control of CMT by Ayrad and CIMR, subject to required regulatory approvals.